

The price gap is a curve, not a wall, and it moves.
The standard story goes: steel is cheap, carbon is expensive, end of discussion. The standard story is thirty years old. The real relationship is a set of curves, material cost, tooling cost, volume, weight value, that cross in surprising places. In some applications, carbon fiber is already the cheaper choice when the full accounting is done. Here is where the curves cross, and why they keep moving.
The Sticker vs the System
Start with the obvious: raw material cost favors steel wildly, roughly an order of magnitude per kilogram. If cost per kilogram were the decision, this article would end here. But nobody buys kilograms. They buy parts, and parts carry tooling, processing, finishing, and logistics costs where the comparison gets interesting. A stamped steel panel requires a stamping die, and production stamping dies cost from tens of thousands to millions of dollars. A carbon mold for the same panel costs a small fraction of that. At low volumes, the curve has already crossed.
Where Low Volume Flips the Math
This is the dirty secret of the performance and specialty market: for production runs in the hundreds or low thousands, composite tooling is so much cheaper than hard metal stamping dies that the total cost per part can favor carbon even at ten times the material price. That is why the aftermarket is built on composites. No one can amortize a stamping die over three hundred hoods for a niche chassis. The carbon steel vs carbon fiber comparison covers the property side; the tooling side is why the parts exist at all.
The Weight Value Multiplier
Now add the value side. In performance applications, weight has a market price. Racing teams have long paid thousands of dollars per kilogram saved; premium car buyers pay it in option packages without blinking. When a kilogram of weight reduction is worth more than a kilogram of the part costs, carbon’s material premium stops being a cost and starts being an arbitrage. Steel cannot play that game at all. It has no way to make a lighter version of itself at any price the market will bear. The carbon fiber manufacturing process explains why even premium carbon production stays economical at these volumes.
The EV Accelerant
Electric vehicles are bending the curves faster. Batteries made cars heavier, commonly 300 to 500 kilograms heavier than their combustion equivalents, and range anxiety made every kilogram of body mass a battery-cost multiplier. Lightweighting now pays twice: once in performance, once in battery size. Premium EV programs are reaching for composite structure at volumes that would have been unthinkable for combustion cars, and every program that scales brings the cost curves down for everyone else, the same way volume always does.
The Automation Question
The curve’s next bend is already visible: automation. Robotic fiber placement and automated tape laying are attacking carbon’s labor problem from the structural end, while compression molding attacks it from the parts end. Each advance cuts the hours per part. And since hours, not fiber, are the cost, each advance moves the crossover point toward higher volumes. Steel’s process, fully automated decades ago, has no equivalent frontier left. One curve is still falling; the other fell long ago. That asymmetry is the whole forecast.
Where Steel’s Curve Still Wins
- High volumes: past a few thousand identical parts, stamping economics bury everything.
- Economy segments: where the buyer’s budget sets the ceiling, steel’s price is the floor.
- Repair-dependent applications: where the service network matters more than the part.
- Heat and structural workhorse zones: exhaust-adjacent, suspension, safety-critical at mass-market prices.
Reading the Curve as a Buyer
The used market plays along with the curve. Carbon parts depreciate slowly because they do not corrode and their condition is visible at a glance. A five-year-old panel in good clear coat holds most of its value. Steel parts depreciate like ordinary car parts. For buyers who think in total cost of ownership rather than sticker price, that gap quietly narrows the difference every single year.
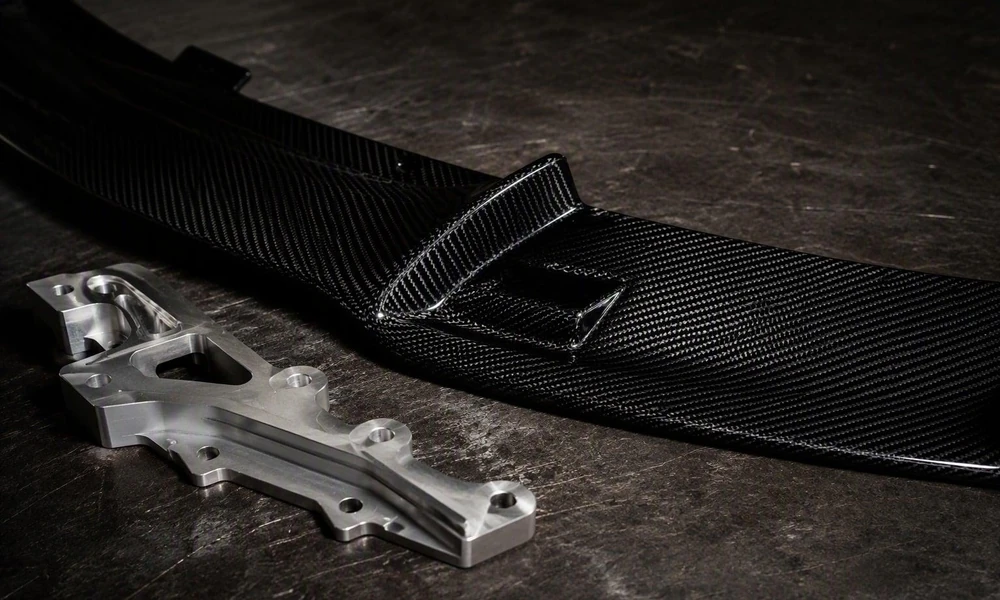
For the individual enthusiast, the practical translation is simple. The carbon parts in the aftermarket catalog, hoods, trunks, wings, aero, exist precisely in the low-volume zone where carbon already wins the total-cost contest. You are not paying an exotic premium; you are buying the economically rational construction method for the volume. The premium you see over a used steel panel is real, but so is the weight saving, and the used market for carbon parts, which do not corrode and hold value accordingly, returns much of it when the build moves on.
Cost curves are not destiny, but they are gravity. Carbon’s curve has been falling for forty years, steel’s tooling curve is fixed, and the crossover zones keep widening. The question is no longer whether carbon makes economic sense. It is whether your application sits in a zone where it already has. And more zones qualify every year.